One Big Beautiful Way to Donate to Charities
Why Donating Appreciated Stock is so Powerful
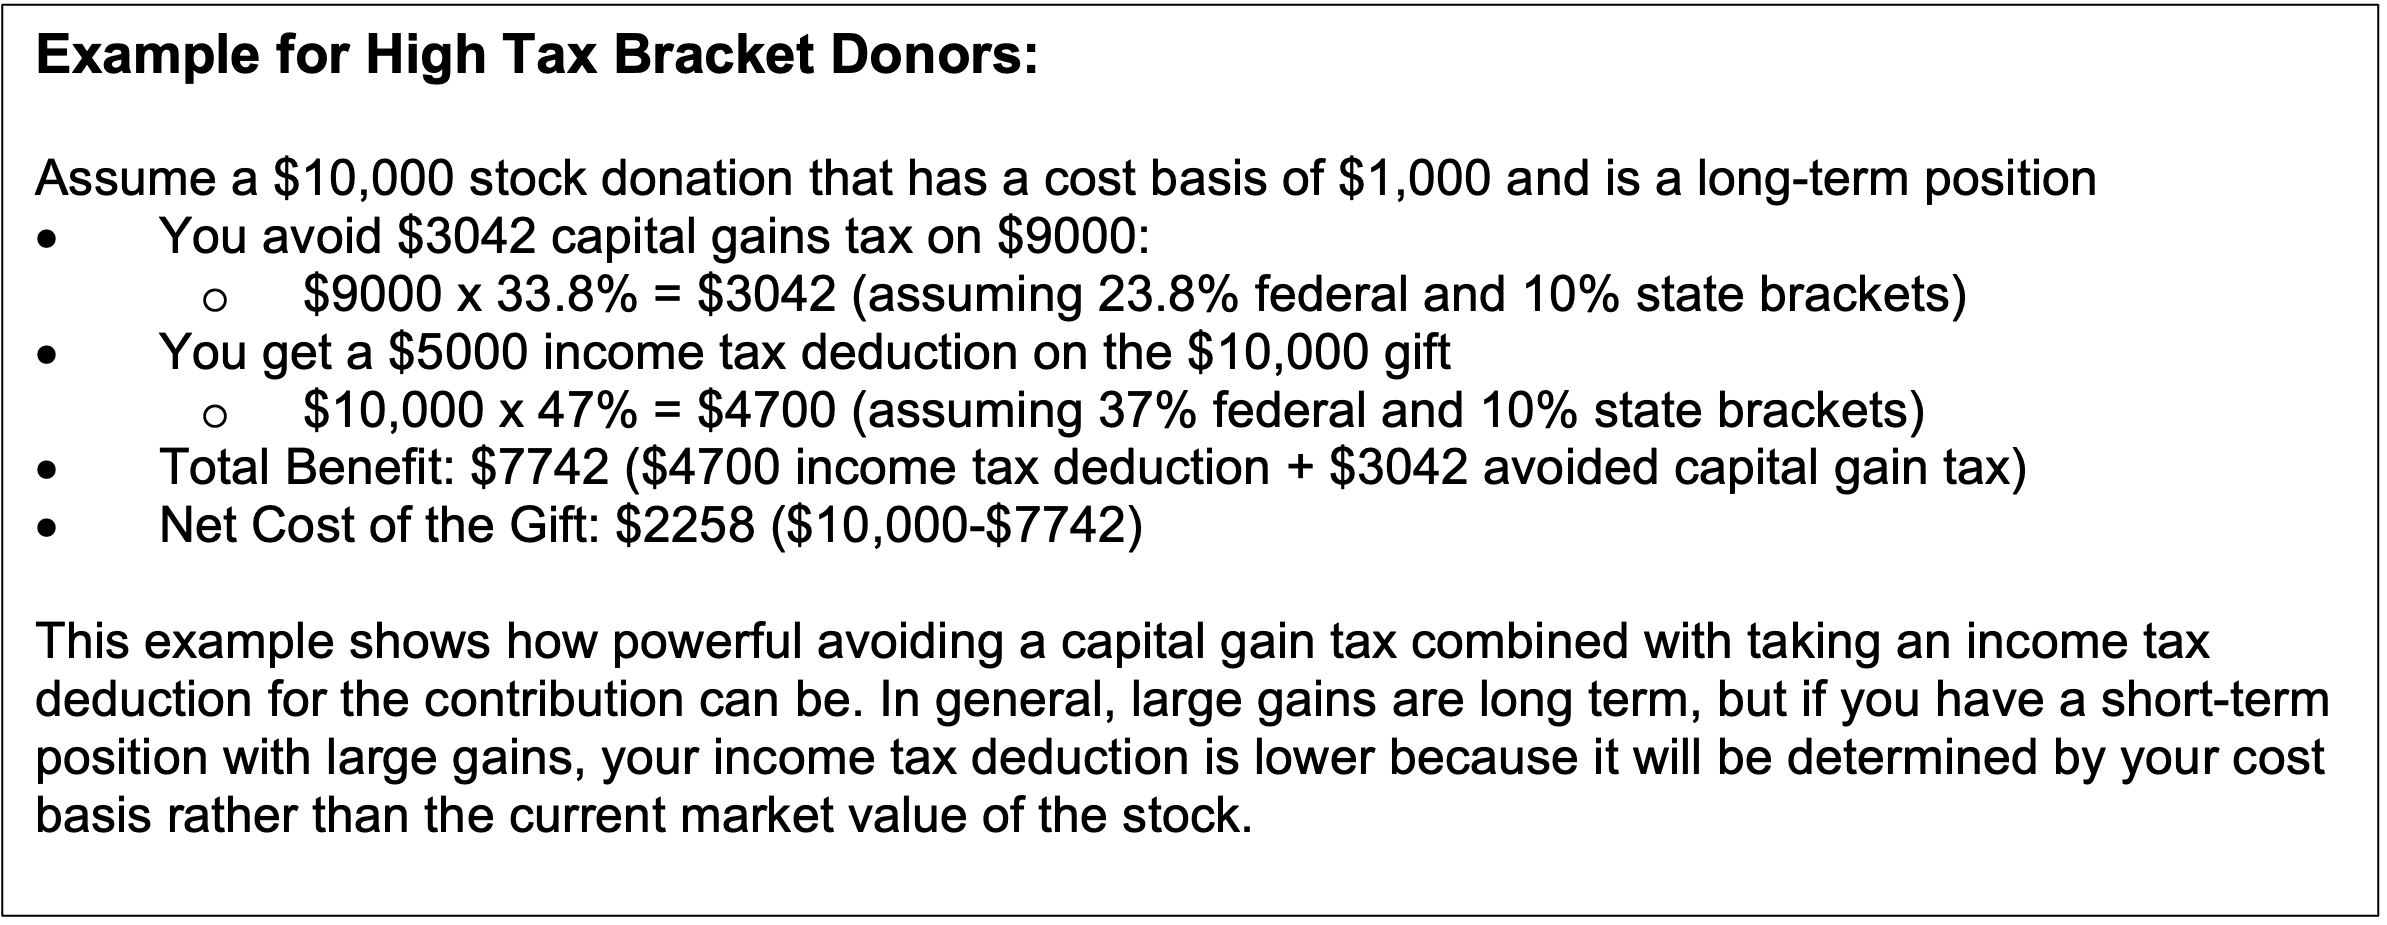
When selling appreciated stock, you recognize capital gains on the difference between the amount you paid and the amount you sell it for.
Alternatively, when donating appreciated stock, you can generally deduct the current market value of the shares from your income, subject to adjusted gross income (AGI) limits. Income limits are often 30% of AGI for gifts to public charities.
With this strategy, you sidestep the capital gains tax you would have owed if you sold first and gave cash from the sale instead.
Since charitable organizations do not pay capital gains tax, the full market value of your donation can be used.
Portfolio Management Benefits
Highly appreciated stock positions can cause your portfolio to be out of balance with excessive exposure to a few companies or market sectors. By strategically donating parts of these large positions, you can bring your portfolio into better balance.Why Earlier in the Year Giving Can Make SenseMany people bunch charitable planning into year end, but if you are specifically worried about a certain stock or ETF underperforming, there is a strong case for making your contribution earlier. By reducing concentration sooner, you can redeploy equity risk into assets you like better, rather than carrying an overweight position when you expect relative underperformance.
Practical Considerations and Caveats
Confirm whether you are donating short or long-term (held > one year) appreciated stock. The tax consequences are different. When donating long term positions you can deduct the full market value. For short-term holdings, you can only deduct the cost basis. In both cases, no capital gains tax is paid, but if you donate short term holdings, you waste the value of the appreciation from a tax standpoint.For example: If you bought a stock for $10,000 which is now worth $100,000 eight months later, your deduction would be $10,000. If you waited and sold it when held for a year, your deduction would be $100,000. However, it might still make sense if you really wanted to reduce your position now because of market risk.
Check AGI limits and potential carryforwards with your tax advisor; large gifts can create multi-year deduction carryovers.
A donor-advised fund can be an efficient hub for giving: you transfer appreciated stock once, take the deduction now, and then make grants to charities over time. AGI limits apply for how much you can deduct in a single year.
Because rules and thresholds can change and state taxes differ, the final step is to run this through your CPA or tax counsel with the stock you intend to contribute and get some AGI projections.
Making Contributions From Traditional IRAs
Once you reach the age where Required Minimum Distributions (RMDs) apply, your traditional IRA stops being a simple tax-deferred account and starts generating mandatory taxable income each year. Every dollar you withdraw as an RMD is generally taxed as ordinary income. That withdrawal can push you into higher tax brackets, increase taxes on Social Security, and raise Medicare premiums.Donating directly from your IRA can be especially useful if you don’t need the money to live on. If you make a Qualified Charitable Distribution (QCD), you can transfer money straight from your IRA to a qualified charity. The amount of the gift counts toward your RMD but is not included in your taxable income. In effect, you satisfy the requirement to withdraw funds without increasing your tax bill.Important Considerations
In 2026, the QCD limit is $111,000 per person. Married couples, each with their own IRA, can contribute $111,000 each.
You can make a QCD starting at age 70 ½ even though you are not yet required to take an RMD.
QCDs are not counted toward the ‘maximum amounts deductible’ for those who itemize charitable giving on their tax returns. This feature means a QCD can potentially allow for a larger charitable gift than otherwise possible if you simply donate cash or other assets.
It Is Beautiful
Donate with stock and support the causes you care about while improving tax efficiency and maximizing the impact of your gift. When combined with thoughtful timing, your donations become a disciplined and highly effective financial strategy.